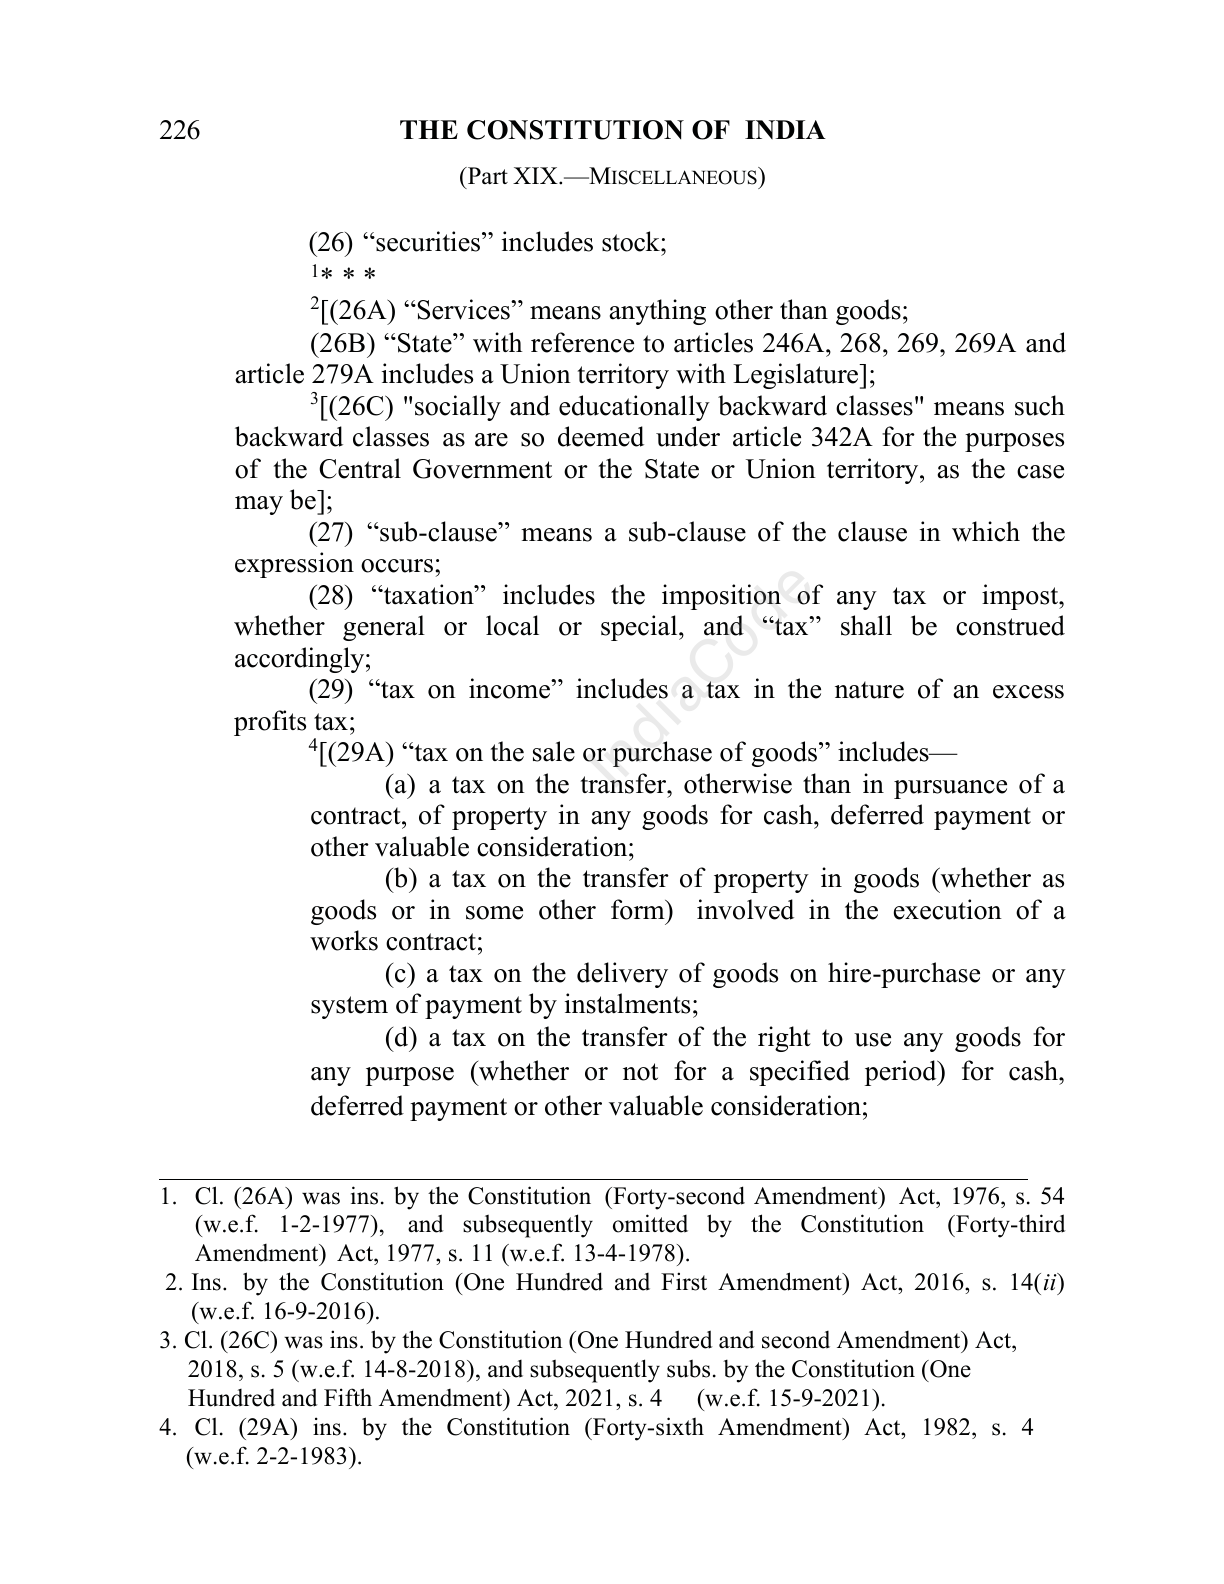
Full physical source page · unreviewed extraction
The Constitution of India in English 2026: page 257
The Constitution of India in English 2026, India Code delivered snapshot ed1820c0a1100c2c, physical page 257, typed edition 223d395df4de00897c78a4c0a752b32348d86f7c4f7013254fd4e03da46ceca0. Unreviewed extraction.
Source: official India Code PDF · catalog record. Fetched 2026-10-19T23:32:36Z. SHA-256 ed1820c0a1100c2c6aa8ece835a8c8a60f996ae7eba30cc1798233683c66cfba.
Legal currency, territorial applicability and extraction fidelity are unverified. Catalog checksum/size differs from the delivered PDF; both identities are retained. Articles, Schedule/appendix material and source footnotes share these physical pages. Compare the full original image.
Source cover/preface date: 10th September, 2026. Preface amendment statement: Constitution (One Hundred and Sixth Amendment) Act, 2023. Embedded PDF title: Constitution of India_ 20 MAY 2026 (final).pdf. These are distinct source labels, not currentness or commencement approval.
Retained layout text
226                  THE CONSTITUTION OF INDIA
                           (Part XIX.—MISCELLANEOUS)

              (26) “securities” includes stock;
              1
                ***
              2
                [(26A) “Services” means anything other than goods;
              (26B) “State” with reference to articles 246A, 268, 269, 269A and
      article 279A includes a Union territory with Legislature];
              3
                [(26C) "socially and educationally backward classes" means such
      backward classes as are so deemed under article 342A for the purposes
      of the Central Government or the State or Union territory, as the case
      may be];
              (27) “sub-clause” means a sub-clause of the clause in which the
      expression occurs;
              (28) “taxation” includes the imposition of any tax or impost,
                                                      e
                                                 od
      whether general or local or special, and “tax” shall be construed
      accordingly;
                                            aC
              (29) “tax on income” includes a tax in the nature of an excess
      profits tax;                      di
              4
                [(29A) “tax on the sale or purchase of goods” includes—
                                     In
                     (a) a tax on the transfer, otherwise than in pursuance of a
              contract, of property in any goods for cash, deferred payment or
              other valuable consideration;
                     (b) a tax on the transfer of property in goods (whether as
              goods or in some other form) involved in the execution of a
              works contract;
                     (c) a tax on the delivery of goods on hire-purchase or any
              system of payment by instalments;
                     (d) a tax on the transfer of the right to use any goods for
              any purpose (whether or not for a specified period) for cash,
              deferred payment or other valuable consideration;


1. Cl. (26A) was ins. by the Constitution (Forty-second Amendment) Act, 1976, s. 54
    (w.e.f. 1-2-1977), and subsequently omitted by the Constitution (Forty-third
    Amendment) Act, 1977, s. 11 (w.e.f. 13-4-1978).
2. Ins. by the Constitution (One Hundred and First Amendment) Act, 2016, s. 14(ii)
    (w.e.f. 16-9-2016).
3. Cl. (26C) was ins. by the Constitution (One Hundred and second Amendment) Act,
   2018, s. 5 (w.e.f. 14-8-2018), and subsequently subs. by the Constitution (One
   Hundred and Fifth Amendment) Act, 2021, s. 4 (w.e.f. 15-9-2021).
4. Cl. (29A) ins. by the Constitution (Forty-sixth Amendment) Act, 1982, s. 4
   (w.e.f. 2-2-1983).
Compare original page image